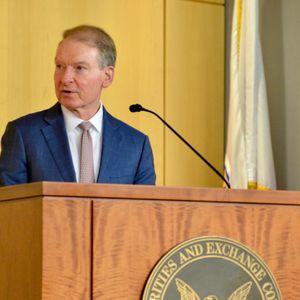
SEC Chairman Paul Atkins has signaled the agency will pursue formal notice-and-comment rulemaking for three emerging categories of financial technology — onchain trading systems, blockchain settlement infrastructure, and AI-driven financial applications — marking a fundamental shift from the enforcement-first approach that characterized crypto regulation under his predecessor Gary Gensler.
The announcement, made at an AI+ Expo in Washington in May 2026, represents the SEC's clearest public commitment yet to providing regulatory clarity through the established administrative law process rather than through litigation outcomes. For U.S. crypto firms that have been operating in legal ambiguity since 2022, the prospect of actual rules — not just enforcement pauses — signals a new phase of regulatory engagement.
Atkins identified onchain trading systems as the first target for formal rulemaking, acknowledging that existing exchange registration requirements were designed for centralized order books and cannot be straightforwardly applied to decentralized protocols that automatically match trades through smart contracts. Blockchain settlement infrastructure represents the second area, particularly as DTCC's tokenization platform and the Nasdaq tokenized settlement rule create new settlement architectures that existing clearinghouse regulations do not address. The third category — automated financial applications and crypto vaults — covers AI-driven portfolio management and yield optimization protocols that combine functions historically spread across multiple regulated intermediaries.
Atkins articulated the core structural mismatch driving the rulemaking initiative: traditional securities regulations were designed for a world where distinct intermediaries perform distinct functions — brokers execute trades, exchanges list securities, clearinghouses settle, custodians hold. Modern blockchain protocols can execute trades, manage collateral, route liquidity, execute strategies, and settle transactions all within a single software system. Applying regulations built for disaggregated intermediaries to integrated protocols creates either over-regulation (treating every protocol function as requiring separate registration) or regulatory blindness (treating the protocol as outside existing rules).
"A single protocol can execute a trade, manage collateral, route liquidity, execute trading strategies through vault structures and settle the transaction. Our regulatory framework needs to account for this reality."
— SEC Chair Paul Atkins, AI+ Expo, Washington, May 2026
Atkins emphasized that the SEC's rulemaking agenda is designed to complement rather than compete with congressional legislation. The CLARITY Act would define jurisdictional boundaries between the SEC and CFTC; the SEC's own rulemaking would fill in the operational details within the SEC's jurisdiction. This coordinated approach — agency rulemaking running parallel to legislation rather than waiting for legislation to complete — reflects the practical reality that formal rulemaking takes years, and the market is not waiting. For policy researchers, the May 2026 announcement marks the beginning of a multi-year regulatory buildout that will define the permanent framework for U.S. crypto markets.
Atkins' commitment to formal notice-and-comment rulemaking carries procedural significance beyond its substantive content. Under the Administrative Procedure Act, rules developed through notice-and-comment are more durable than guidance documents, staff statements, or informal agency positions — the tools that the Gensler-era SEC primarily used to signal its crypto enforcement priorities. APA-compliant rules can be challenged in court, but they are presumptively valid and can only be overturned by showing the agency acted arbitrarily or contrary to statutory authority. Guidance documents, by contrast, have no such protection and can be withdrawn overnight.
For the crypto industry, Atkins' rulemaking approach represents a double-edged development. On the positive side, formal rules provide statutory certainty that informal guidance cannot. Companies that structure their compliance programs around APA rules have legal protection that companies relying on informal SEC positions do not. On the negative side, the rulemaking process takes years — typically three to five years from initiation to final rule, with additional time for legal challenges — meaning that the regulatory certainty Atkins is promising will not arrive quickly. The crypto market will continue operating in ambiguity during the rulemaking period, relying on the administration's enforcement posture rather than formal rules to define the boundaries of permissible activity.
Keywords: SEC, Paul Atkins, onchain markets, AI finance, crypto rulemaking, CLARITY Act, blockchain regulation
Source: CoinDesk